BY SAL GRECO
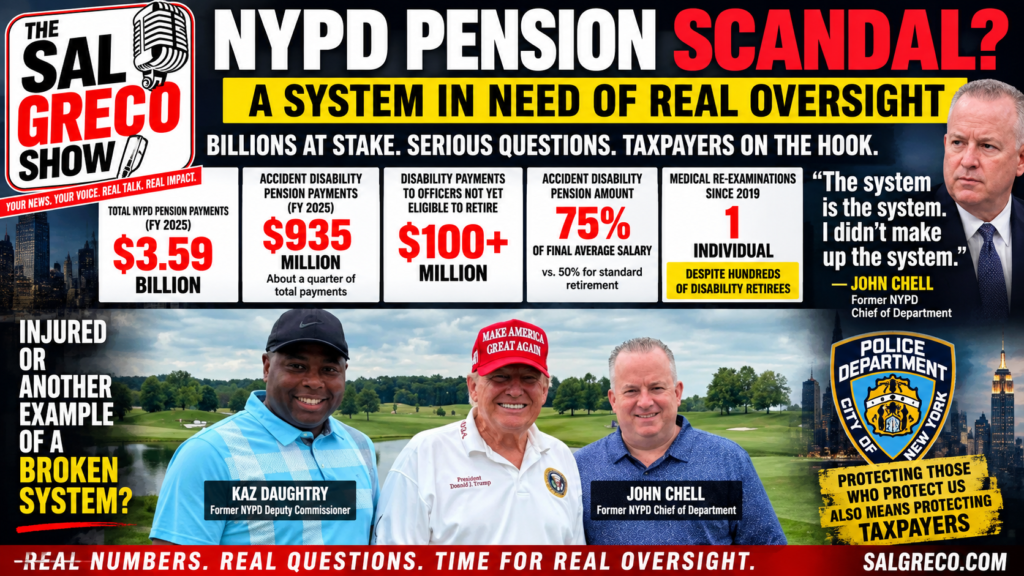
When former NYPD Chief of Department John Chell defended his lucrative accident disability retirement by saying, “The system is the system. I didn’t make up the system,” he may have inadvertently summarized the central problem now identified by New York City’s own Department of Investigation.
DOI released a sweeping report Tuesday examining the New York City Police Pension Fund’s administration of accident disability retirement benefits. Its conclusion is not that police officers injured in the line of duty should be denied the benefits they have earned. Quite the opposite: those protections exist for an important reason. But DOI found vulnerabilities in the system that create a risk of improper payments, weak oversight and potentially enormous costs to New York City taxpayers.
And Chell’s case became one of the report’s most striking examples.
A Nearly $296,000 Pension and a Fundamental Question
According to the DOI report, citing public reporting, Chell retired at the end of 2025 after approximately three years at the highest levels of the NYPD’s uniformed leadership, serving first as Chief of Patrol and then as Chief of Department. Following an ankle injury suffered in July 2024, Chell applied for and received an accident disability retirement package worth $295,919.64 annually.
The issue DOI raises is not whether Chell injured his ankle. Nor does DOI accuse Chell of fraud or conclude that he was legally ineligible for his pension.
The issue is how the system decided whether he was disabled.
The Police Pension Fund’s Medical Board generally evaluates applicants against the “essential functions” of a police officer. Those functions can include apprehending criminals, handling emotionally disturbed people, crowd control and physically subduing resisting suspects.
That means Chell, despite serving as Chief of Department, would have been evaluated on whether he remained capable of performing physical functions such as grappling with a resisting suspect—not simply whether his ankle injury prevented him from performing the actual responsibilities of the NYPD’s highest-ranking uniformed position.
That distinction matters.
If someone’s actual position is primarily executive, administrative and managerial, should that person qualify as disabled because he can no longer perform physical duties ordinarily associated with a street officer?
DOI believes the question is serious enough to warrant changing the system.
DOI Says There Are Significant Legal Questions
This isn’t merely a disagreement over policy.
DOI says there are “significant questions” about whether the Police Pension Fund’s reliance on generic essential police functions instead of an applicant’s actual duties is consistent with the law.
The report compares New York City’s approach with the system applicable to New York State police officers. DOI notes that state cases have interpreted “performance of duty” to mean the individual’s actual duties, not the generalized duties of a police officer.
DOI therefore recommended that the PPF adopt regulations, training and guidance requiring disability applications to be evaluated according to an officer’s actual job duties.
Remarkably, the Police Pension Fund rejected that recommendation.
The Chell Review Exposed Another Problem
The examination of Chell’s application revealed something else that should concern taxpayers.
When the Pension Fund’s Board of Trustees considered whether Chell’s injury occurred within the scope of his duties, members debated exactly what the Chief of Department actually does.
One trustee observed:
“It’s an administrative position.”
Another argued that fieldwork constituted a “leadership function.”
Even more surprisingly, DOI says one member of the Board resorted to information found online to determine what the responsibilities of the Chief of Department were.
Think about the implications.
A government pension system potentially responsible for hundreds of thousands of dollars annually to a single retiree was evaluating a claim involving the NYPD’s highest-ranking uniformed official, yet DOI says a trustee had to search online for information about what the applicant’s job actually entailed.
DOI subsequently recommended procedures requiring individualized information concerning an applicant’s real duties, specifically noting that this would prevent the PPF from having to “speculate about the scope of an applicant’s duties, as the PPF had to do when assessing John Chell’s application.”
That isn’t a minor administrative flaw. It demonstrates why independent oversight and clearly defined standards matter.
“The System Is the System”
When the Daily News previously asked Chell about his disability retirement, he responded:
“The system is the system. I didn’t make up the system.”
DOI apparently found those words significant. The agency placed the statement prominently at the beginning of its report, immediately before its executive summary.
And Chell is correct about one thing: an individual applicant does not create the pension system.
But that is precisely why the system itself must be scrutinized.
A properly functioning pension system should not depend on assuming every applicant is honest, nor should it assume every disability determination made at retirement will remain accurate forever. Good government requires controls capable of identifying mistakes, changed medical circumstances and intentional fraud.
That protection matters both to taxpayers and to the overwhelming number of genuinely injured officers whose legitimate disability benefits should never be tainted by weaknesses that can be exploited by others.
Almost $1 Billion a Year
The numbers make the need for oversight impossible to dismiss.
The Police Pension Fund makes retirement payments to more than 50,000 retired NYPD officers. In fiscal year 2025, total pension payments reached approximately $3.59 billion.
Of that amount, approximately $935 million went to accident disability retirees.
More than $100 million went to disability retirees who otherwise had not yet reached the age or service requirements necessary for retirement.
Accident disability is also considerably more lucrative than ordinary service retirement in many cases: Tier II and Tier III ADR recipients receive 75% of their final average salaries, regardless of length of service.
With that much taxpayer money involved, safeguards shouldn’t merely exist on paper.
They should actually be used.
The Most Alarming Finding May Be What Happens After Retirement
New York City law already provides a mechanism for checking whether certain disability retirees remain unable to work.
The Pension Fund can call eligible disability pensioners back for medical re-examination. If someone is determined capable of gainful employment and the Board agrees, procedures exist to return that person to available City employment and adjust pension payments under specified circumstances. Refusing a required examination can result in discontinuation of the pension.
So how often has this safeguard been used?
According to DOI, since 2019 the PPF has required only one individual to undergo medical re-examination under this provision.
One.
DOI described the Fund’s re-examination program as “virtually non-existent.” The agency went even further, concluding that the PPF’s near-total failure to use the safeguard was not simply an exercise of discretion and “must be corrected.”
That should get every taxpayer’s attention.
DOI Found Cases That Demonstrate Why Re-Examination Matters
The report describes four anonymized disability retirees whose activities raised questions.
DOI received information alleging that one retiree with a shoulder injury was lifting weights, performing extensive renovations and operating a manual-labor business. Investigators reviewed material allegedly showing him bench pressing heavy weights and participating in a contact sport.
Another officer had retired after the Medical Board found limitations in the range of motion of his arm. DOI later found social-media videos apparently showing him performing complicated dance routines with full arm movement and doing numerous pushups.
Another individual allegedly instructed high-intensity workout classes, while a fourth operated a business involving frequent travel and heavy equipment, although DOI says the evidence concerning that fourth individual was mixed.
Those examples do not establish fraud, and DOI specifically says it did not pursue criminal investigations against Officers A through D.
But that’s precisely the distinction policymakers need to understand.
A suspicious photograph or Instagram video should not automatically cost someone a pension. At the same time, credible evidence that someone’s physical condition has substantially improved should not simply be ignored.
The answer is due process plus meaningful re-examination.
Build a System That Checks Itself
DOI ultimately issued five recommendations: evaluate applicants according to their actual job duties; establish rules governing medical re-examinations; require certain disability retirees to periodically certify that their disability continues; establish a public intake system for relevant information; and consider medical re-examinations for the four anonymized retirees identified in the report.
The PPF accepted only the final two. It rejected the recommendations concerning actual job duties, systematic re-examinations and periodic disability certifications.
That should not end the conversation. It should begin one.
New York City should conduct a comprehensive review of the disability pension system and determine whether stronger statutory, regulatory or administrative controls are necessary.
There should be individualized job-duty assessments. There should be periodic reviews where medically appropriate. There should be random audits where legally permissible. There should be a mechanism for credible tips. There should be meaningful consequences for knowingly false claims, while simultaneously protecting legitimate retirees from baseless accusations.
And there should be transparency about how enormous disability pensions are approved—whether the applicant is a rookie police officer or the Chief of Department.
The Taxpayer Shouldn’t Be the System’s Safety Net
Police officers who suffer genuine career-ending injuries protecting New Yorkers deserve the benefits promised to them. Nothing in DOI’s report changes that.
But protecting legitimate disability pensions and protecting taxpayers from abuse are not competing goals. A strong oversight system accomplishes both.
No pension program distributing nearly $1 billion in accident disability benefits annually should operate on an honor system. The possibility of fraud, medical improvement or erroneous initial determinations is precisely why safeguards exist.
And when credible evidence raises questions, the system should be capable of answering them.
John Chell’s case is significant not because DOI proved that Chell did anything improper—it did not. In fact, DOI explicitly says it expresses no opinion on whether his application would have been approved had his actual duties been used as the standard.
Its significance is that the former Chief’s case exposed the peculiar mechanics of the system at the highest possible level.
Chell said, “The system is the system. I didn’t make up the system.”
Fair enough.
But when that system controls billions in public money, taxpayers have every right to demand that the system continually prove it is working—and that it has enough checks built into it to identify those who may be exploiting it.
Because ultimately, when the system fails to check itself, New York City’s taxpayers are the ones left holding the bill.